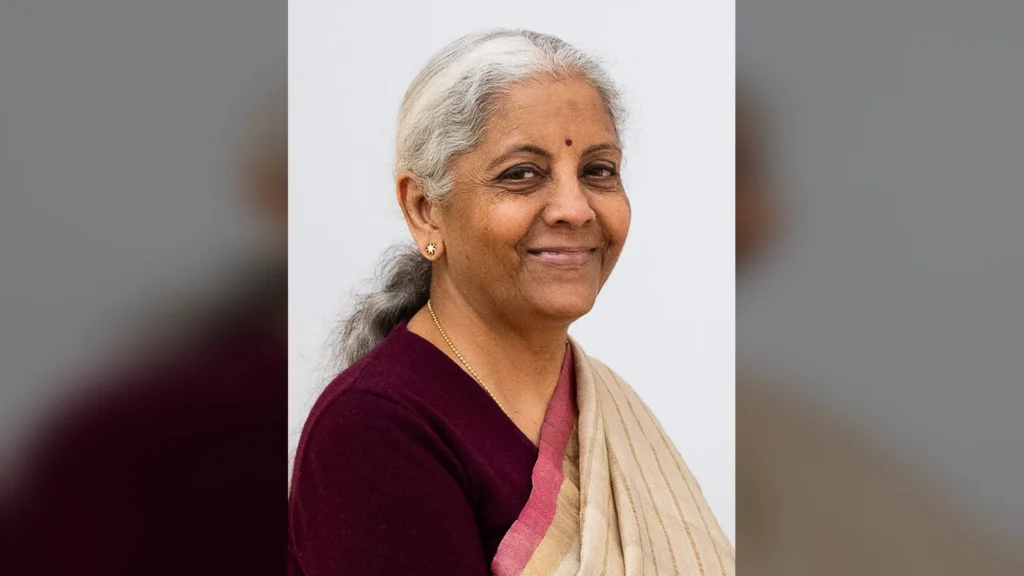
NEW DELHI — Finance Minister Nirmala Sitharaman said on Tuesday that India can achieve a growth rate above 10% if technology, innovation and the startup sector are fully leveraged. Speaking at the IIT Madras Dialogue on Economic Growth in Bengaluru, she urged the private sector and government agencies to deepen collaboration on research, digital infrastructure and venture funding.
Growth target and current performance
Sitharaman noted that the country’s real GDP grew 7.2% in the 2025‑26 fiscal year, a pace that remains above the global average but falls short of the 10%‑plus potential she believes is attainable. She cited the rapid expansion of the digital economy, which contributed roughly ₹12 trillion to GDP in 2025, as evidence that technology can act as a multiplier for overall growth.
Role of startups
The minister highlighted the startup ecosystem as a key engine for job creation and export earnings. India now hosts more than 70,000 registered startups, according to the Ministry of Commerce, and the sector attracted ₹3.5 trillion in venture capital in the last financial year. Sitharaman said the government will expand the Startup India programme, streamline approvals for high‑impact ventures and increase the tax exemption ceiling for profits reinvested in research and development.
Policy measures announced
In the dialogue, Sitharaman announced three measures aimed at accelerating technology adoption:
- A ₹1.2 trillion fund to support deep‑tech and artificial‑intelligence projects in partnership with private investors.
- An amendment to the Income Tax Act that raises the deduction limit for R&D expenditure from 150% to 200% of eligible costs for firms with annual turnover above ₹5 billion.
- A rollout of high‑speed broadband in 150 tier‑2 and tier‑3 cities by 2028, funded through a public‑private partnership model.
These steps are intended to address bottlenecks in capital access, regulatory clearance and digital connectivity that have constrained scaling for many Indian innovators.
International competitiveness
Sitharaman referenced the Global Innovation Index, where India moved to 31st place in 2026, up from 38th the previous year. She said the upward trajectory reflects the combined impact of policy reforms, increased R&D spending and a growing pool of skilled engineers graduating from institutions such as IIT Madras.
Reactions from the business community
Industry bodies, including the Confederation of Indian Industry (CII), welcomed the announcements, calling them “timely” and “aligned with the needs of a digital‑first economy.” Venture‑capital firms said the new fund and tax incentives could unlock an additional ₹4 trillion of private investment over the next three years.
Challenges ahead
Analysts cautioned that achieving a sustained 10% growth rate will require addressing structural issues such as labour market rigidity, supply‑chain bottlenecks and the need for upskilling the workforce. The Reserve Bank of India’s latest monetary policy report, released in August, projected growth of 7.5% for FY 2026‑27, citing inflationary pressures and global uncertainty as headwinds.
Outlook
Sitharaman concluded that while the 10% target is ambitious, the convergence of a vibrant startup ecosystem, robust digital infrastructure and targeted fiscal incentives creates a credible pathway. She urged state governments to align their industrial policies with the national vision and pledged regular monitoring of the new initiatives through a joint task force chaired by the Ministry of Finance.
Primary Sources & Official Records
- Sitharaman on India’s 10%+ growth potential: Startups and technology can drive next phase
- Nirmala Sitharaman backs India’s 10% plus growth potential, highlights role of startups, t
- Union Finance Minister Smt. Nirmala Sitharaman Makes Key Announcements on India’s Economic
- India can achieve over 10% growth with technology, innovation: Sitharaman – Bodhi Wire