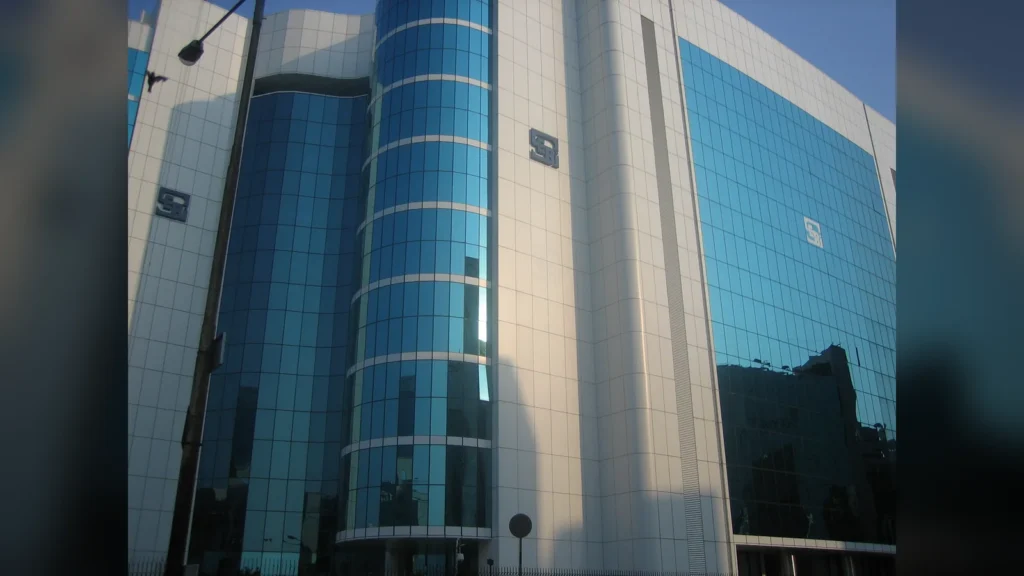
NEW DELHI — The Securities and Exchange Board of India (SEBI) is reviewing a proposal that would permit stock exchanges to list their own securities on the platforms they operate. The move has drawn criticism from market participants who warn of a conflict of interest, while regulators argue the model could streamline capital‑raising for exchanges.
Regulatory rationale
SEBI officials say the self‑listing framework is intended to broaden capital‑market depth and provide exchanges with an additional source of funding for technology upgrades and market‑infrastructure projects. The board’s draft guidelines, circulated to market participants in early September, outline eligibility criteria, disclosure requirements and a supervisory mechanism designed to prevent undue influence over listed securities.
Industry pushback
Industry leaders have voiced reservations about the proposal. The National Stock Exchange (NSE) chairman, in an interview reported by Business Standard on 25 September 2026, urged a reconsideration of self‑listing, citing the potential for “regulatory capture” and the difficulty of maintaining an arm’s‑length relationship when an exchange is both regulator and listed entity.
Other exchanges and broker‑age firms have echoed similar concerns, arguing that the model could erode investor confidence if market participants perceive that listed exchanges enjoy preferential treatment in trading, fee structures or corporate actions.
SEBI’s conflict‑of‑interest safeguards
In response, SEBI officials highlighted a series of safeguards embedded in the draft. The board proposes that any exchange seeking to list must obtain prior approval from an independent committee comprising members from the Ministry of Finance, the Reserve Bank of India and senior officials from SEBI itself. The committee would assess the exchange’s governance standards, audit reports and compliance history before granting a listing permit.
SEBI also plans to impose a mandatory lock‑up period of 12 months on the exchange’s own shares, during which the entity cannot engage in share‑buyback or dividend distribution without explicit board approval. Additionally, the regulator intends to subject self‑listed exchanges to heightened surveillance, including quarterly reporting of order‑flow data and transaction‑level disclosures to the market watchdog.
Comparative perspective
Self‑listing is not unprecedented globally. The United Kingdom’s London Stock Exchange and Japan’s Tokyo Stock Exchange have listed subsidiaries, but both operate under separate corporate structures and are subject to distinct regulatory oversight. SEBI’s draft notes these precedents while emphasizing that India’s market architecture differs, necessitating a “conservative regulatory model” to mitigate systemic risk.
Potential impact on market dynamics
Analysts note that if approved, self‑listing could unlock capital for exchanges to invest in new trading platforms, data‑analytics tools and cross‑border connectivity. However, they caution that any perceived advantage could distort competition among exchanges, especially if listed entities receive preferential access to market‑making services or lower transaction fees.
Investor groups have called for a transparent public consultation process. The Securities Industry Development Council (SIDC) has submitted a formal request to SEBI for a 30‑day extension to the comment period, seeking clarification on the proposed supervisory committee’s composition and the criteria for evaluating conflicts of interest.
Next steps
SEBI has scheduled a stakeholder meeting for 10 October 2026 in Mumbai, where the draft guidelines will be discussed in detail. The regulator has indicated that the final policy could be issued by the end of the fourth quarter, pending the outcome of the consultation.
Until then, market participants are expected to monitor the regulatory discourse closely, as the decision will shape the governance framework of India’s capital markets for years to come.