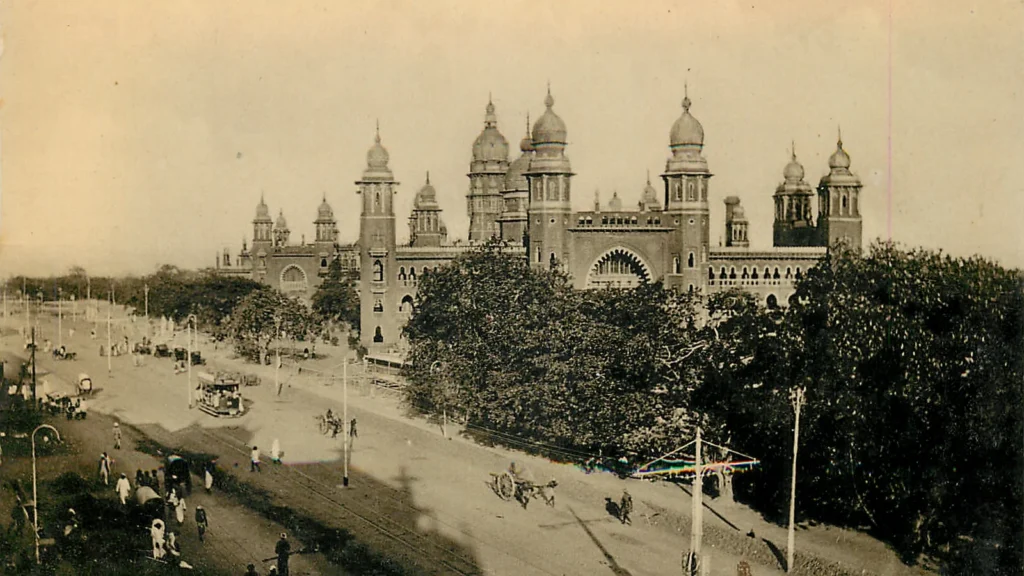
CHENNAI — The Madras High Court on Thursday, 8 October 2026, ruled that borrowers cannot mortgage their constitutional rights with banks. The court said that a pledge of a fundamental right is void because such rights are not property that can be alienated.
Fundamental Rights Are Inalienable
The decision arose from a dispute in which a borrower, Mr. R. Kumar, had taken a ₹12 million loan from a private lender. The bank demanded that he pledge his right to education as collateral, arguing that the right could be treated as a form of intangible property. Mr. Kumar challenged the demand, contending that the pledge violated his constitutional rights.
The High Court rejected the bank’s position, stating that the right to education, enshrined in Article 21A of the Constitution, is a fundamental right that cannot be transferred or mortgaged. The court noted that fundamental rights are “inherent and sacrosanct” and that any attempt to treat them as collateral would undermine the constitutional guarantee.
Legal Framework and Precedent
In its judgment, the court cited the Supreme Court’s ruling in *State of Tamil Nadu v. S. R. Ramaswamy* (2024), where it was held that fundamental rights are not property and cannot be alienated. The court also referenced the principle that the Constitution protects rights “from being used as collateral for private gain.”
Under the Indian Contract Act, 1872, a pledge must be of a property that can be transferred. The court emphasized that intangible rights, such as the right to education, do not meet this criterion. Consequently, the bank’s demand was declared void and unenforceable.
Implications for Banking Practices
The ruling has immediate implications for banks that routinely ask borrowers to pledge collateral. While banks can demand tangible assets—such as land, buildings, or vehicles—this decision clarifies that they cannot seek intangible, constitutional rights as security. The court’s judgment is likely to prompt banks to review their loan agreements and ensure compliance with constitutional safeguards.
Financial regulators, including the Reserve Bank of India, have long cautioned banks against overreaching in collateral demands. This judgment reinforces that caution and provides a judicial benchmark for permissible collateral.
Broader Context of Loan Collateral in India
India’s banking sector has seen a surge in unsecured loans, but secured loans still dominate the market. Collateral is a key risk mitigation tool for lenders, and the typical collateral includes real estate, movable assets, and in some cases, intellectual property. However, the concept of pledging a constitutional right is unprecedented and has not been addressed in prior jurisprudence until now.
The High Court’s decision is expected to influence how banks draft loan agreements, particularly in the context of consumer credit. The judgment may also prompt legislative scrutiny of clauses that inadvertently allow banks to demand intangible rights.
Madras High Court’s Role in Constitutional Interpretation
The Madras High Court, established in 1862, has a long history of adjudicating matters involving constitutional law. Its rulings often set precedents that are followed by other courts in the country. This latest judgment adds to that legacy by reaffirming the inviolability of fundamental rights.
Legal experts note that the court’s decision aligns with the broader constitutional doctrine that fundamental rights are not subject to contractual negotiation. The ruling is expected to be cited in future cases where banks or other institutions seek to leverage intangible rights as collateral.
Conclusion
By declaring that constitutional rights cannot be mortgaged, the Madras High Court has reinforced the principle that fundamental rights are sacrosanct and inalienable. The decision serves as a clear warning to banks that any attempt to treat such rights as collateral will be struck down by the judiciary.